
As a developer, CasaMax Inmobiliaria stays ahead on the topics that matter most to each of its clients.
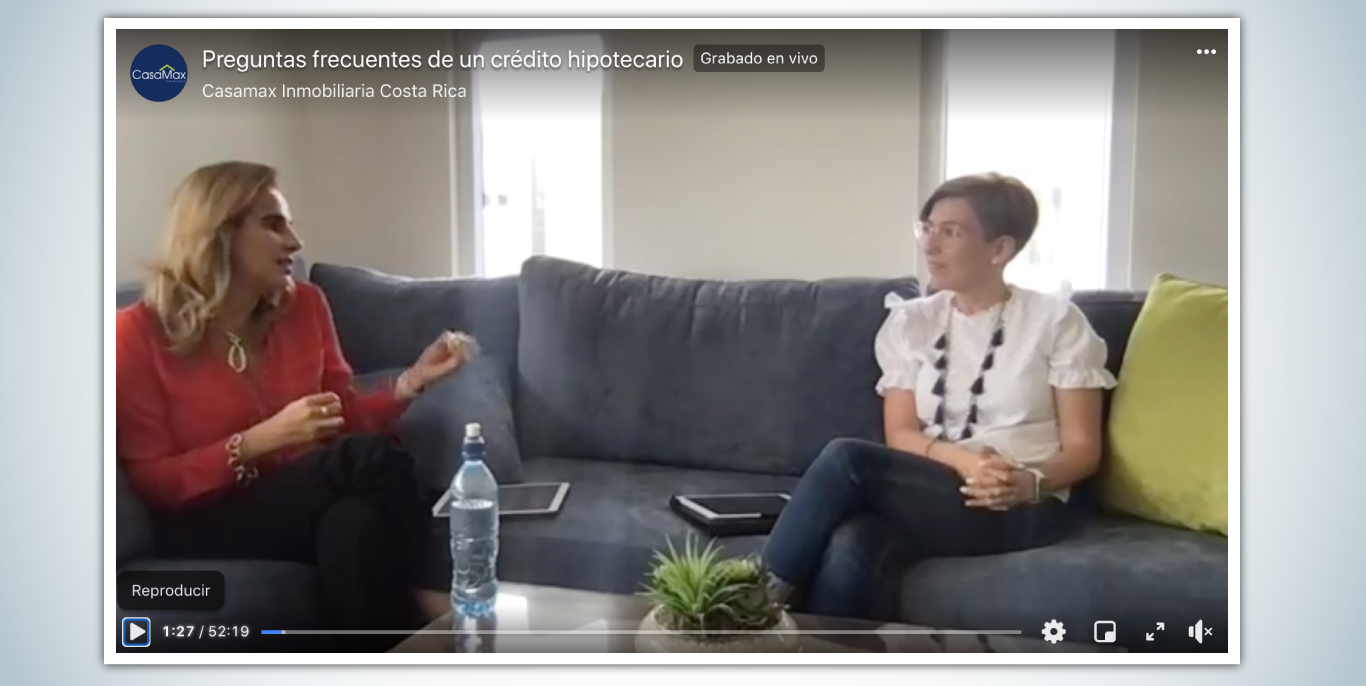
That is why we held a live stream with staff from Scotiabank to answer, together, the most frequent questions buyers may have.
For everyone who hasn't had the time to watch the live stream available on our social media, this blog post walks you through everything that was discussed in the video.
The interview featured Michelle Peralta, CasaMax Sales Advisor, and María José Acuña, Scotiabank Product Manager, who covered every detail.
The home loan was the main topic the interview began with. It has different conditions than a general loan, since its purpose is to give a person or family the chance to live in their own home in the future.
“The important thing is for people to get over the fear a bit. People usually think that taking out a home loan means a huge debt over a huge term, but if I do it properly and understand the features of that loan, I'll be able to handle it in an orderly way without harming my finances,” said Acuña.
There are several factors to consider before taking the step:
Is now a good time to do it?
Should I wait?
Do I need to save up for the down payment?
And the best approach is to learn each of the requirements so you know whether you can meet them, so that in the end it is a dream come true and not a stumbling block.
Debt was also discussed. Both speakers agreed that borrowing is not bad if it is done the right way and paid on time; it ends up being something positive, since you build a good credit history.
In addition, Peralta pointed out that, as contradictory as it may sound, now is a good time to buy a home, because given the economic slowdown, both developers and banks are offering better terms.
The bank requirements were also covered, depending on the type of worker, whether salaried or self-employed:
Salaried employee
-6 months of continuous employment at the same company
-Review of a good credit history
-Personal information
-Employer letter (income)
Self-employed
-Personal information
-Proof of income (gross and net)
-Economic activity you work in
-How long you have been working in that activity
-Income and expense report prepared by a certified public accountant (CPA)
Another requirement is the down payment, which ranges between 10% and 20% of the home's total value. Here, the benefits offered by the developer play a very important role: if the home is purchased in presale, you can make down payment installments while the formalization process is underway.
This brings up one more topic, which is the debt level required to qualify for the loan. It comes down to how much of a person's or family's income goes to fixed expenses (debt payments), which should be between 30% and 40% of the total amount.
This analysis is performed by the bank and is not set in stone, since it can be adjusted to the client's profile and the level and types of debt they have.
Another relevant topic mentioned in the interview was insurance, where María José stated that the two policies that cannot be missing are life and fire insurance, and they are already included in the set monthly payment.
Life insurance is a safeguard: if the borrower passes away, this coverage pays off the outstanding loan balance.
And depending on the client's profile, unemployment insurance is also offered as a way to protect your assets.
Mortgage loan vs. Trust
These are two legal structures for obtaining a home loan, and they differ from each other.
The mortgage is the best-known and therefore most widely used. At the time of formalization, everything is put in the buyer's name, and the buyer must pay a significant amount for the costs of the process.
With a trust, by contrast, the client does not have to pay as much money up front but rather at the end, when the transfer takes place, since the property is held in the name of a trust.
Which one is better? That depends on each person's or family's situation or profile, and your bank advisor will help you make the best decision.
You should think carefully when taking out a home loan and choosing the currency, since banks offer different benefits depending on whether the loan is in colones or dollars.
On top of that, there is the interest rate: for the first 3 or 5 years you will have a fixed rate (depending on the loan), and for the remaining years a variable rate that behaves volatilely.
In any case, for the topics covered in this interview or any other questions you may have, the sales advisors at CasaMax Inmobiliaria and your preferred bank will help you clear them up.
We invite you to watch the full interview on our social media, both on:
Facebook https://fb.watch/5h4k0qA54V/
And on Instagram https://www.instagram.com/tv/CNikVgeqgYA/?igshid=1ashidmrwci5t